Big Changes Coming to Consumer Credit Reporting in the UK: What It Means for You
The UK’s financial watchdog is overhauling the way it collects data from consumer credit firms, impacting how over 40 million consumers are protected and supervised.
As part of its effort to become a more data-savvy and efficient regulator, the Financial Conduct Authority (FCA) has rolled out a new consumer credit return. This new return is designed to replace two existing regulatory reports, with plans to eventually phase out four more. The goal? Simplify oversight, reduce red tape for firms, and focus regulatory efforts where consumers face the greatest risks.
What’s Changing?
The new return will apply to firms engaged in key consumer credit activities, including:
- Credit broking
- Debt counselling
- Debt adjusting
- Providing credit information services

According to the FCA, this updated return will streamline data collection, helping firms focus on reporting that truly matters—data that leads to better outcomes for both consumers and the market.
“We’re cutting unnecessary bureaucracy so we can concentrate on protecting consumers where the risk is highest.”
Industry Input Has Shaped the Reform
The FCA didn’t make this shift alone. Through consultation with industry stakeholders and feedback from firms, the regulator adopted a more practical and proportionate approach. In fact, 28% of the originally proposed questions were removed—a win for clarity and reduced reporting burdens.
The new return will be tailored to each firm’s business model, making it more relevant and less intrusive. This means firms will now spend less time on generic questions and more time on data that reflects their real-world operations.
Why It Matters for Consumers
This isn’t just a backend change. The consumer credit sector supports more than 40 million individuals in the UK, many of whom are financially vulnerable. The improved data collected through the new return will allow regulators to better identify areas of harm, track trends, and step in earlier when issues arise.
A Temporary Pause on Additional Changes
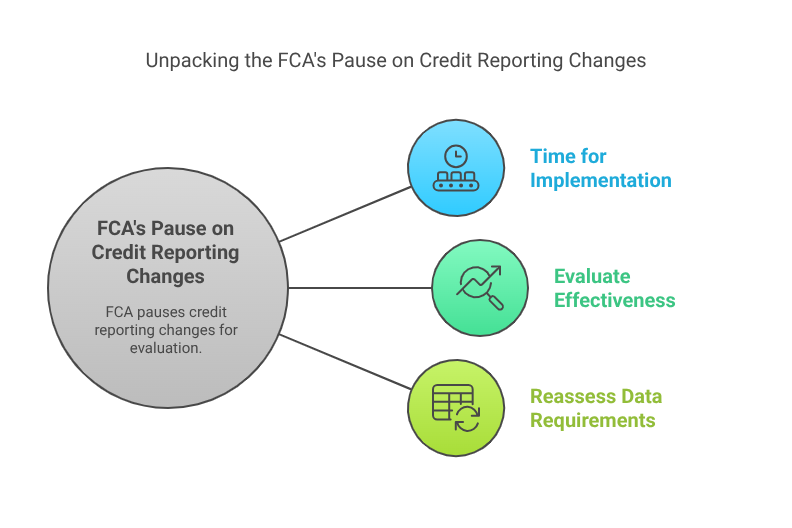
Although the FCA initially planned to roll out additional changes across all consumer credit returns, it has decided to pause future updates. This pause is intended to:
- Give firms time to implement the current changes
- Evaluate the effectiveness of the new return
- Reassess long-term data requirements
This measured approach ensures that the pace of regulatory change doesn’t overwhelm firms, especially smaller businesses, while maintaining focus on consumer protection.
🔗 Final Thoughts
This is a major shift in how the UK’s financial ecosystem handles consumer credit data. For consumers, it could mean better protections and more responsible oversight of the firms that manage credit, debt advice, and related services.
For businesses, it’s a chance to align more closely with regulatory expectations while benefiting from a less burdensome, more logical reporting process.
📰 Stay up to date with more financial regulation and credit industry insights at TalkinDebts.org